WORLD→INDIA
Owed money by an Indian company
For overseas suppliers, service providers, lenders and insurers with an unpaid Indian B2B receivable.
B2B debt collection, receivables management and dealer, customer or vendor verification—for Indian businesses, overseas creditors and Indian exporters.
Domestic, Government and cross-border receivables follow different payment paths.
For overseas suppliers, service providers, lenders and insurers with an unpaid Indian B2B receivable.
For Indian exporters managing an unpaid overseas receivable, including insured and ECGC-sensitive matters.
For companies that need Revenue Assurance or Revenue Realization across corporate, dealer or Government receivables.
START WITH THE WORK YOU NEED DONE
WHEN NORMAL FOLLOW-UP IS NOT ENOUGH
Old balances, scheme claims and missing ownership need a consistent work plan.
Dealer duesTrace the submitted invoice, acceptance and customer-side payment event.
Post-sale invoicesTrack retention, deposits and guarantees as distinct release objects.
Project close-outsWe don't touch the money your sales team sells. We collect the money nobody owns.
For agreed domestic engagements, GGA’s six-month operating objective is recovery or an evidenced account classification. This is not a recovery guarantee; scope, debtor response and legal proceedings can change the timetable.

The intervention changes with the age and cause of the receivable.
Use Revenue Assurance and Invoice Lifecycle Management to keep valid invoices payment-ready, visible and owned.
Use Revenue Realization to expose the real cause, unlock evidence and ownership, and manage a credible route to cash.
Recorded in a one-year project-business engagement as at June 2022. A further 20% was classified as collectable and under follow-up; 10% was classified as customer-service or no-intent issues.
Review the engagement and evidence boundary →TRADE CHANNEL · SIX-MONTH RESULTThe assignment also separated collectable accounts, service issues, missing counterparties and cases requiring a different route.
See the operating dashboard →Feedback highlights improved receivables discipline and the value of GGA working closely with the client's team.
Feedback highlights communication, persistence and the value received from the working relationship.
Anonymous comments supplied by GGA management and edited lightly for clarity. Client-reported results describe individual engagements, are not a general forecast and have not been independently verified for publication. Names and logos remain confidential.
Request a confidential reference discussionGGA’s internal benchmarks, based on collections by value across Revenue Assurance and Revenue Realization engagements spanning multiple clients and sectors.
Methodology note: These are rolling internal averages rather than a fixed-cohort study. Invoice age is calculated from the invoice date. The underlying portfolio changes continually as debtor accounts are added, collected, removed or reclassified. Disputed, insolvent and other difficult receivables remain included while actively managed. Matters transferred to legal proceedings and accounts subsequently removed under GGA’s ‘Risk’ classification are excluded from later calculations. Outcomes vary by documentation, dispute status, debtor circumstances and timing of intervention.
These descriptive internal benchmarks are not a forecast, guarantee or probability of recovery for an individual invoice or portfolio. Read the evidence, exclusions and comparison →
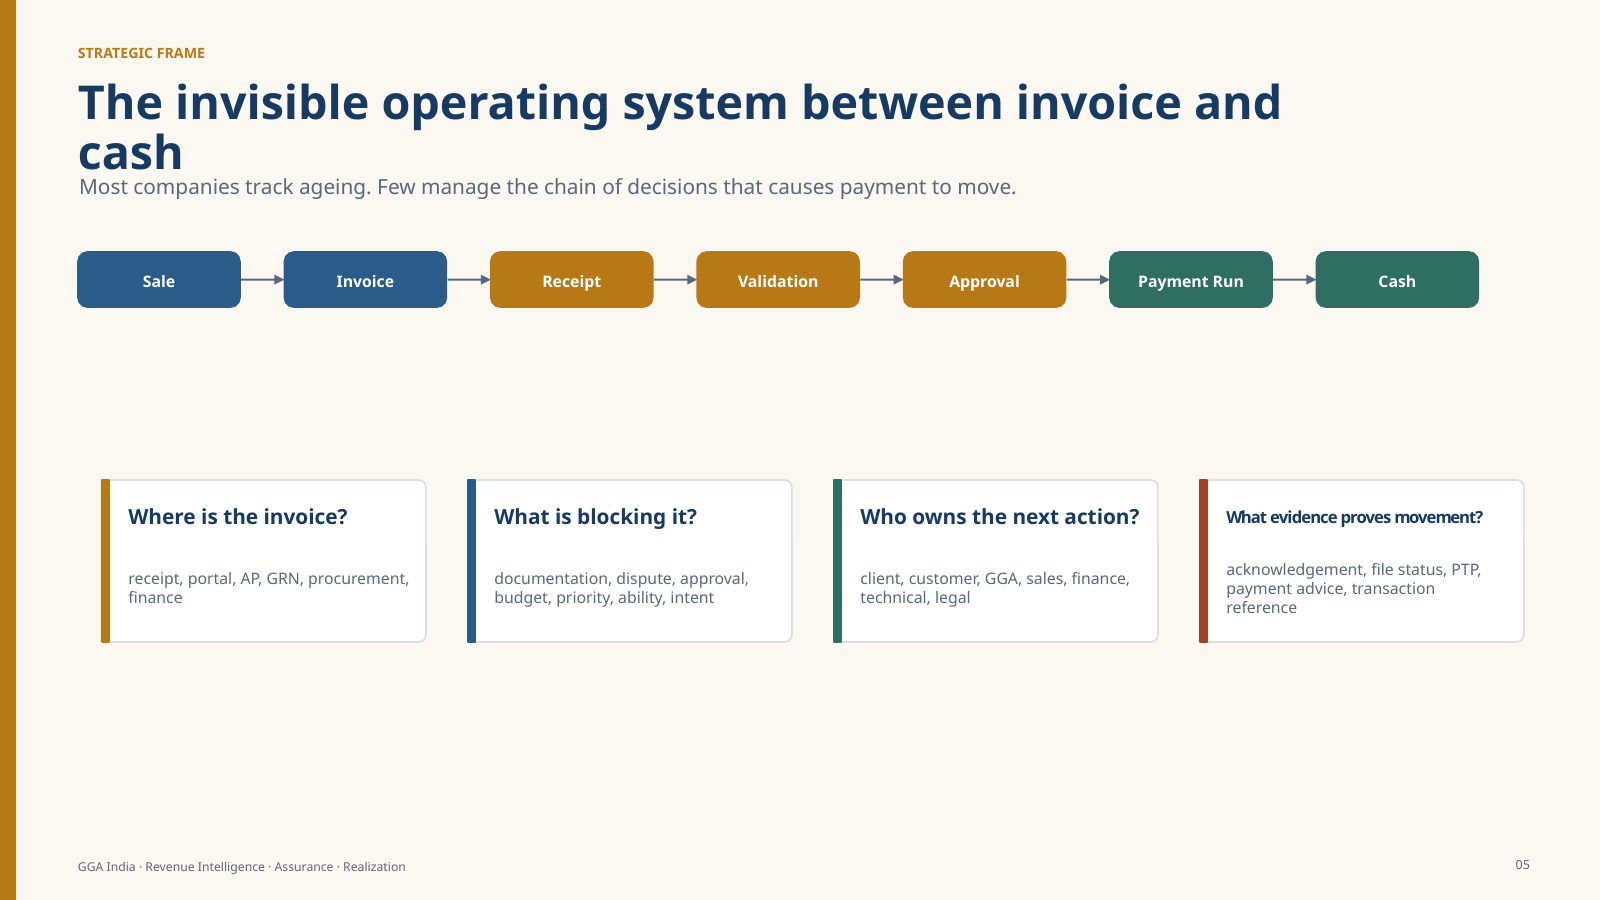
Follow the invoice through submission, acceptance, approval, payment proposal and cash—with one visible owner and next event.
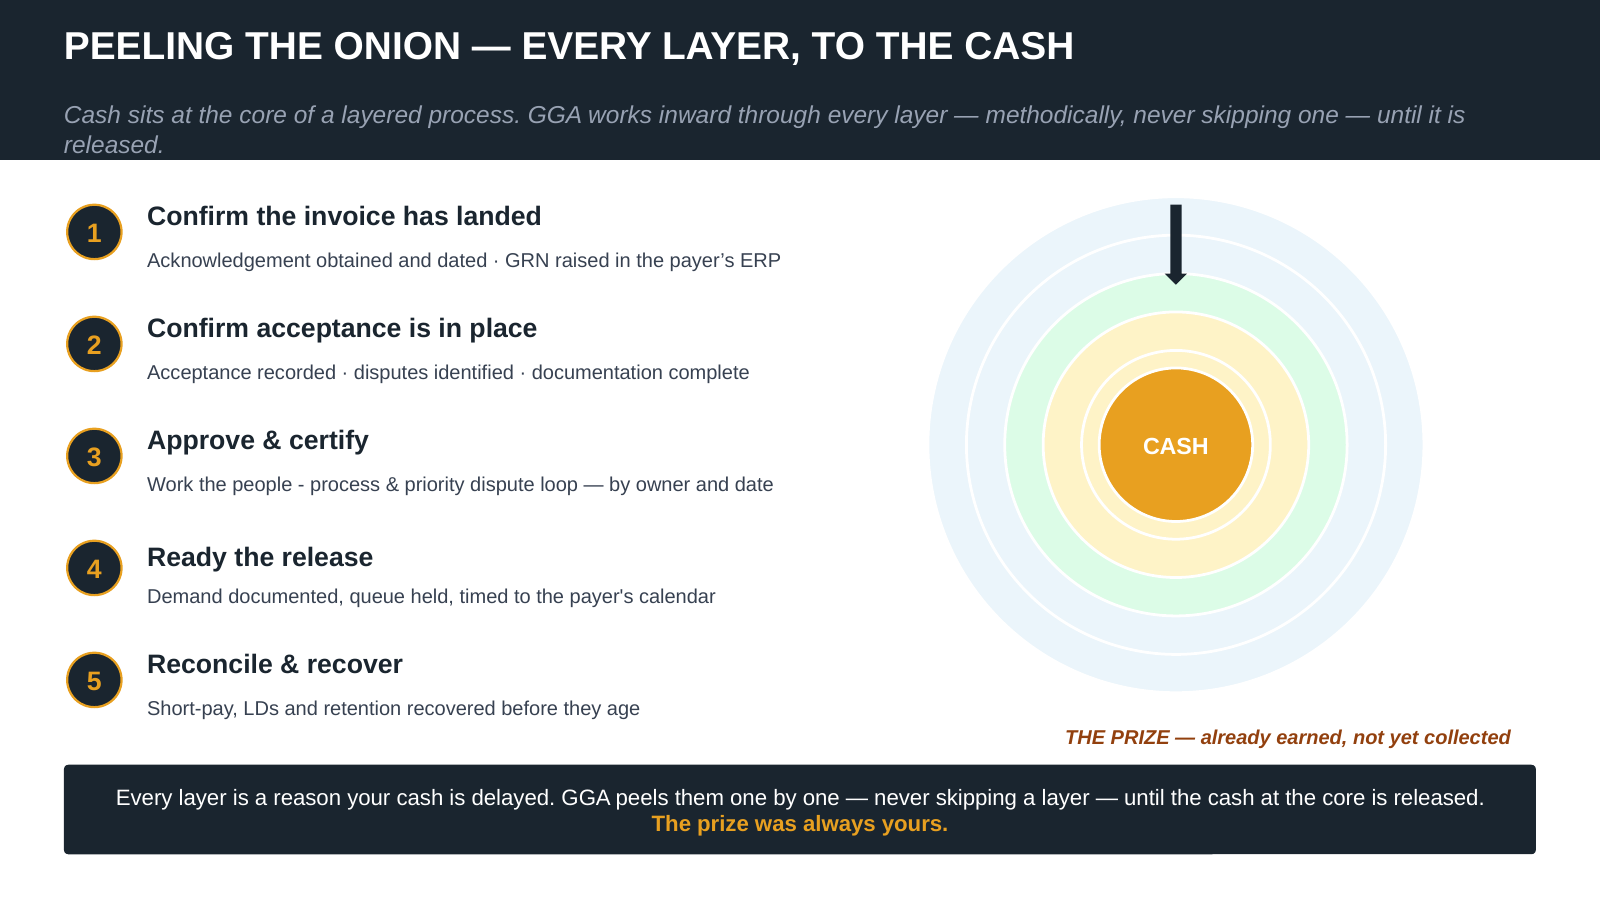
Move beyond the stated excuse, then unlock evidence, ownership and the customer payment process together.
Why evidence, liquidity, people and available recovery routes often deteriorate as unpaid invoices age.
Estimate simple financing or carrying cost. The number updates as you type.
1,00,00,000 INR × 12.0% × 90 days ÷ 365
All monetary results: INR (₹).Enter full units of the selected currency. Changing the currency changes labels and number formatting only; it does not convert amounts.Method: Outstanding Amount × Annual Cost of Capital × Delay Days ÷ 365. Excludes management time, opportunity cost, recovery cost and bad-debt risk.
Named ownership, a defined reporting rhythm, an escalation ladder and an open-items register support focused engagements. B2B engagements can include up to 1,000 accounts per client; dealer and distributor portfolios can extend to 7,500 cases.
A conceptual management view—not a prediction for an individual account.
Conceptual management framework. The curves show direction, not universal recovery percentages or a forecast for a live matter.
GGA research examines how revenue becomes receivable, why payment is delayed and how financial, commercial and operating evidence should inform management decisions.
Explore GGA's case evidence across projects, healthcare, pharmaceuticals, agri-inputs, trade channels and Government receivables.
View case studies →Founder Perspectives examines the commercial decisions and payment behaviours behind the ageing report.
Read Founder Perspectives →